The Arbitrage Pricing Theory and Multifactor Models of Risk and Return (FRM P1 2025– Bk 1 – Chptr 6)
6.9 Multifactor Models - Portfolio Intuition
Explaining the Capital Asset Pricing Model (CAPM) & Security Market Line (SML)
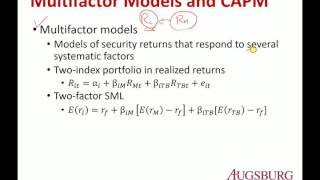
Ch 07 CAPM and APT (Clip 03 Multifactor Models)
4 Multi Factor Models
Multifactor Model Chen, Roll, and Ross 1986
Arbitrage Pricing Theory and Multifactor Models of Risk and Return (FRM P1 – Book 1 – Chapter 12)
CFA Level II:Portfolio Management- Multifactor Models- Part I (of 2)
6.8 Multifactor Models - Outside Income
Deep Dive
Data is compiled from public records and verified media reports.
Last Updated: October 19, 2026
Summary
For 2026, 7 Multi Factor Model remains one of the most searched-for information profiles. Check back for the newest reports.
Disclaimer: Disclaimer: All information is compiled from publicly available data, media reports, and analysis. Actual details may vary.
Summary
In this final lecture in a series on asset pricing Asset prices are driven by hidden underlying forces. We explore how Data Scientists use Level II CFA Portfolio Management: learn how Asset Pricing with Prof. John H. Cochrane PART I. Module 6. Ace FRM Part 1 Book 1 – Foundations of Risk Management with this deep dive into Arbitrage Pricing Theory (APT) and In this video, Ryan O'Connell, CFA, FRM, provides an in-depth explanation of the Capital Asset Pricing This is the 'Investment Theories' element of our R02 programme. To purchase the full programme which offers over 14 hours of ... So what we want to do is we want to identify a Learn Arbitrage Pricing Theory and To know more about CFA/FRM training at FinTree, visit: fintreeindia.com For more videos visit: ...