Background of Expected Shortfall Conditional Tail Expectation
Looking for the latest information on Expected Shortfall Conditional Tail Expectation? We've researched comprehensive data, records, and insights about Expected Shortfall Conditional Tail Expectation.
Key Details
Explore the key sources for Expected Shortfall Conditional Tail Expectation.
Recent Updates
Stay updated on Expected Shortfall Conditional Tail Expectation's latest milestones.
Financial Engineering Course: Lecture 13/14, part 1/2, (Value-at-Risk and Expected Shortfall)
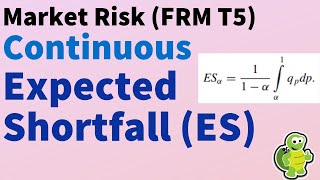
Expected shortfall: approximating continuous, with code (ES continous, FRM T5-03)
CVaR Expected Shortfall
Expected Shortfall for Discrete Distribution - Solved Example (FRM Part 1, FRM Part 2)
Risk Management in Finance: 14. Value at Risk and Expected Shortfall
Risk Management 5B: Value at Risk (continued) and Expected Shortfall
7. Value At Risk (VAR) Models
Financial Engineering Course: Lecture 13/14, part 2/2, (Value-at-Risk and Expected Shortfall)
VaR and Expected Shortfall Clearly & Simply Explained
IQF Chapter 6 (Risk Measures)
Detailed Analysis
Data is compiled from public records and verified media reports.
Last Updated: October 18, 2026
Conclusion
For 2026, Expected Shortfall Conditional Tail Expectation remains one of the most talked-about information profiles. Check back for the latest updates.
Disclaimer: Disclaimer: All information is compiled from publicly available data, media reports, and analysis. Actual details may vary.
Summary
0:57 - Value at Risk (VaR) Explained 3:40 - This video seeks to explain the ES is a complement to value at risk (VaR). ES is the average loss in the In this lesson, we will discuss the Financial Engineering: Interest Rates and xVA Lecture 13- part 1/2, Value-at-Risk and In my previous video, I showed you how we retrieve This video first explains Value at Risk and then explain the logic and formula of CVaR, applies 100 day return data of S&P 500 ... In this video from the curriculum of FRM Part 1 and FRM Part 2, we take a look at Risk Management in Finance 2023, Kiss Gábor Dávid Reading: John C. Hull (2018): Risk Management and Financial Institutions, ... How to address the limitations of value-at-risk? One of the most famous techniques used to measure This is the second part of Lesson 5. Topics: - The VaR for empirical distributions - The MIT 18.S096 Topics in Mathematics with Applications in Finance, Fall 2013 View the complete course: ... Designed for CFA and FRM Part 1 candidates, this video clearly and simply explains the Risk Management concepts of Value at ... ... semi-variance, value-at-risk (VaR) and
What is the most accurate information about Expected Shortfall Conditional Tail Expectation?
Our platform aggregates the most comprehensive and up-to-date insights, ensuring you get relevant details about Expected Shortfall Conditional Tail Expectation.
Why is Expected Shortfall Conditional Tail Expectation trending right now?
Interest in Expected Shortfall Conditional Tail Expectation has surged recently as more people seek reliable resources, related media, and detailed analysis.
Where can I find related media and updates for Expected Shortfall Conditional Tail Expectation?
You can explore extensive galleries, video summaries, and related content directly on this page.
How often is the content about Expected Shortfall Conditional Tail Expectation updated?
We regularly update our database with the latest information, media, and analysis related to Expected Shortfall Conditional Tail Expectation.