Looking for the latest information on Structural Var Using Jmulti? We've compiled comprehensive data, records, and insights about Structural Var Using Jmulti.
Key Details
Explore the primary sources for Structural Var Using Jmulti.
Recent Updates
Stay updated on Structural Var Using Jmulti's latest milestones.
Structural VAR using Eviews
Introduction to the Structural Vector Autoregression (SVAR)
Structural VAR (SVAR) in EViews: Theory, Identification, and Interpretation
SVAR in Eviews
VAR using Stata Eviews Gretl JMulti
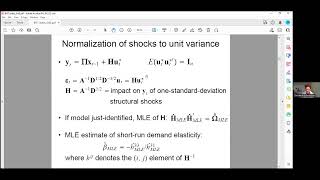
Advances in Using Vector Autoregressions to Estimate Structural Magnitudes
What is the Vector Autoregressive (VAR) Model
Structural Vector Autoregressive (SVAR) Modelling in Eviews
Econometric, JMulTi Time Series Analysis (Introduction)
Structural VAR
How to import data and produce to Impulse response in JMulti
Detailed Analysis
Data is compiled from public records and verified media reports.
Last Updated: October 19, 2026
Final Thoughts
For 2026, Structural Var Using Jmulti remains one of the most searched-for information profiles. Check back for the newest reports.
Disclaimer: Disclaimer: All information is compiled from publicly available data, media reports, and analysis. Actual details may vary.
Summary
Providing private online courses in Econometrics Research Presented by James H. Stock, Harvard University and NBER Recent Developments in In this video, I provide a clear and practical explanation of Why model only one time series at a time? We can do multivariate time series modeling This video provides some useful steps on how to estimate a Structural Autoregressive ( One of the fantastic software that I found besides Matlab is