Looking for the latest information on Expected Shortfall Explained Simply? We've gathered comprehensive data, records, and insights about Expected Shortfall Explained Simply.
Key Details
Explore the main sources for Expected Shortfall Explained Simply.
History
Stay updated on Expected Shortfall Explained Simply's latest milestones.
Expected Shortfall Clearly Explained | FRM Part 1 |Valuation and Risk Models Book 4
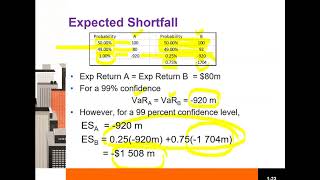
Expected shortfall (Conditional Tail Expectation)
FRTB Transition from Value at Risk to Expected Shortfall Explained Simply
Expected Shortfall Explained with Excel Model|FRTB
Chapter 9 part 4
Computing the Expected Shortfall - Portfolio and Risk Management
Concept of Expected Shortfall | CA Final Risk Management | Sanjay Khemka Classes
Expected Shortfall: An Introduction (FRM Part 1, Book 4, Valuation and Risk Models)
FRM: Expected Shortfall (ES)
Coherent Risk Measures & Expected Shortfall Explained | VaR vs ES
15 Expected Shortfall The Risk Metric Regulators Prefer
Deep Dive
Data is compiled from public records and verified media reports.
Last Updated: October 17, 2026
Future Outlook
For 2026, Expected Shortfall Explained Simply remains one of the most talked-about information profiles. Check back for the latest updates.
Disclaimer: Disclaimer: All information is compiled from publicly available data, media reports, and analysis. Actual details may vary.
Summary
Designed for CFA and FRM Part 1 candidates, this video clearly and Unlock the secrets of financial risk management with Ryan O'Connell, CFA, FRM, as he dives deep into During the financial crisis of 2008, one particular measure of risk became very popular. Many financiers and government officials ... Hello Candidates, In this video we will be talking about the concept of In this video, we break down one of the most critical updates in the Fundamental Review of the Trading Book (FRTB): the ... Hello everyone this is the last video this week and in this video I will be discussing In this Video Sanjay Sir has discussed the basic concept of In this short video from FRM Part 1 curriculum, we introduce this risk measure ES is a complement to value at risk (VaR). ES is the average loss in the tail; i.e., the In this video, we explore Coherent Risk Measures and I'm Fernando Hernandez. While most managers focus on Value at Risk, regulators increasingly require