Looking for the latest information on Vasicek Model? We've researched comprehensive data, records, and insights about Vasicek Model.
Important Facts
Explore the main sources for Vasicek Model.
Latest News
Stay updated on Vasicek Model's latest milestones.
Vasicek Model for Credit Risk Capital (FRM Part 1 Valuation & Risk Models, FRM Part 2 Credit Risk)
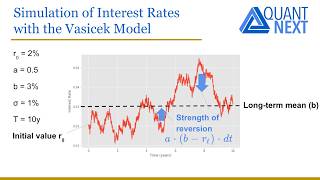
Modelling interest rates: Vasicek model explained (Excel)
Vasicek Model
Vasicek Model Vs Cox Ingersoll Ross (CIR) Model (FRM Part 2, Book 1, Market Risk)
Calibration Vasicek Model to Historical Data | Stochastic Processes in Finance
Marginal PDs used for Vasicek model
Construction de la courbe des taux d'intérêts | Vasicek | Projet Actuariat sur Python
DAP_V8_3: Vasicek Bond Pricing
Vasicek Portfolio Loss Model: Distribution and Quantile
6.10 Comments on Single-Factor Vasicek
FRM Part 2 Topic 1 Vasicek model
Full Guide
Data is compiled from public records and verified media reports.
Last Updated: October 20, 2026
Final Thoughts
For 2026, Vasicek Model remains one of the most searched-for information profiles. Check back for the latest updates.
Disclaimer: Disclaimer: All information is compiled from publicly available data, media reports, and analysis. Actual details may vary.
Summary
In this video, we explore the fundamental differences between arbitrage-free and equilibrium In this video, we introduce the Financial education for everyone Mastering the In this video for FRM Part I and FRM Part II, we explore the Now we're going to look at the vas In this video from the FRM Part 2 curriculum, we take a comparative look at two one factor short term interest rate In this video, we will present the estimation of the parameters of the The images explain how to derive marginal Probability of Default (PD) from cumulative PDs using the Chapitres: 00:00 • Introduction 00:40 • Définition du problème 01:52 • Partie pratique Contact : mazouzinsight Here is a valuation example from fixed-income markets. Apply the Q-pricing methodology to determine the term structure of ... Contains a step-by-step derivation of the Asset Pricing with Prof. John H. Cochrane PART II. Module 6. Bonds More course details: ...